What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
To insure a luxury watch well, first find out whether your existing homeowners, renters, or condo policy covers it for the losses you care about and for enough money. Then give the insurer a clear record of the watch’s identity, ownership, and value—and confirm how a claim would be settled. An appraisal is not automatically required: documentation rules and coverage terms vary by insurer, policy, location, and insured amount.
Start with the coverage you already have
A home policy may cover a watch as personal property, but a jewelry or watch sublimit, deductible, exclusions, or limits on covered events can leave a valuable piece underinsured. Chubb characterizes typical homeowners watch and jewelry limits as $5,000 or less; that is its general consumer-page description, not a universal limit. Liberty Mutual says jewelry sublimits are often between $1,000 and $2,500, also as general guidance rather than a rule for every policy. Check your own declarations and wording rather than relying on either figure.
As an Amazon Associate I earn from qualifying purchases.
Ask your insurer whether the watch can remain under general contents coverage, should be individually scheduled through an endorsement or floater, or needs a separate valuables policy. Options described by US insurers include Liberty Mutual’s scheduled personal property endorsement and separate valuables policies, and Travelers’ Personal Articles Floater and Valuable Items Plus endorsement. Availability, eligibility, limits, and terms vary by insurer and state.
Windows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallOutdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchBuild a file for each watch
Keep identity and ownership evidence distinct from evidence of value. Together, these records help the insurer identify the item, establish that it belongs to you, and assess the amount of coverage requested.
#1 Best Overall
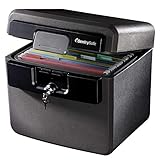
- FIRE AND FLOOD PROTECTION FOR ESSENTIAL PAPERS: UL Classified to withstand high temperatures for up to thirty minutes and ETL Verified to protect contents during water exposure, helping safeguard critical paperwork during common home emergencies
- DESIGNED FOR IMPORTANT DOCUMENT STORAGE: Spacious interior fits hanging file folders and is ideal for organizing passports, birth certificates, insurance records, and legal paperwork
- KEY LOCK SECURITY YOU CONTROL: Durable key lock helps prevent unauthorized access and keeps the lid securely closed during fire events. Two keys are included for backup access
- HOME FRIENDLY SIZE WITH PORTABLE DESIGN: Compact footprint fits easily in closets, offices, or under desks while remaining portable enough to relocate when needed
- BUILT FOR EVERYDAY PEACE OF MIND: Black exterior offers a clean, neutral look that blends into home or office spaces while providing dependable document protection year round
- Identity: brand, model or reference, serial number, and a description of distinctive features.
- Ownership: purchase date and source, receipt or bill of sale, and any available warranty card or box records.
- Condition and appearance: dated photographs of the dial and front, caseback, clasp and bracelet, plus distinctive marks.
- Value and coverage: the amount you want insured, the supporting receipt or appraisal, and the accepted policy schedule.
Photograph the watch, box, and warranty card if available, and scan paper records. Liberty Mutual recommends keeping identifying details, photos, and receipts in an inventory; TH March’s UK checklist also asks for the receipt and photographs of the watch, box, and warranty card. Limit access to images showing serial numbers and share those identifiers only with the insurer, appraiser, or another trusted party when needed.
Ask what value the insurer wants
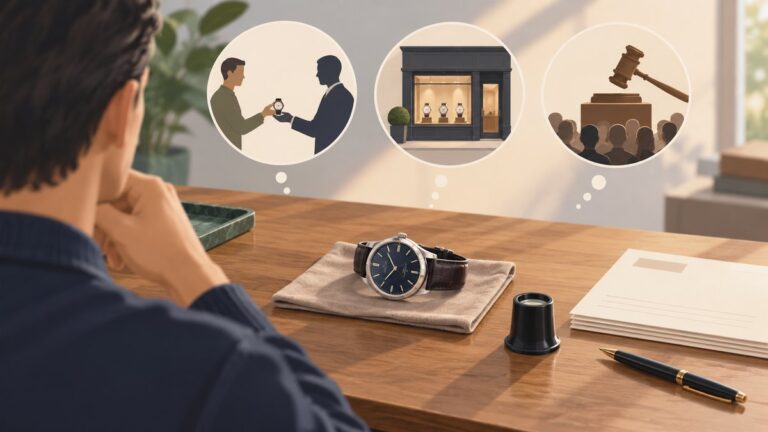
The amount you paid, a current market estimate, a replacement price, and the amount a policy pays after a claim are not necessarily the same. Before arranging an appraisal, ask the insurer what evidence it accepts and what value basis should appear on the document. Find out whether a receipt or bill of sale is enough for your watch and insured amount, or whether an appraisal is required.
Ask the insurer or appraiser to clarify:
- Whether an appraisal is required for this watch and insured amount, and whether the appraiser must inspect it.
- Who may prepare the appraisal, how recent it must be, and what currency it should use.
- Whether the requested figure is replacement value, second-hand replacement value, or another defined basis.
- Whether the insurer must accept the documents by a deadline before coverage begins.
Requirements can differ substantially. Chubb says its US jewelry policy requires an invoice or recent appraisal for items over $100,000; that is a product-specific threshold, not a general insurance rule. Travelers says an appraisal is not necessarily required and that documentation depends on the item and policy.
Rank #2

- Ultimate Fireproof & Water-Resistant Protection: Keep your valuables safe with our DocSafe Hard-Shell fireproof file organizer. It is made of thickened silicone coated fireproof heat insulated cotton material and hard-shell material which can stands up against fire and passed the UL94 -V0/5VA flame retardant test. Fireproof box is both fireproof and water-resistant, ensuring your documents stay protected during fires, floods, or wet weather. It may fit both letter and legal-size files
- Upgraded Hard-Shell Design Fireproof Box: Our fireproof document box combines hard-shell construction with fireproof materials, offering unmatched protection and durability. Unlike traditional soft case, our design withstands extreme conditions while maintaining a sleek, professional look. The Non-dusty material actively repels dust,hair and stains, keeping your box clean and tidy for years. It’s the ultimate solution for safeguarding your important documents, laptop, and valuables
- Large-capacity: Outside size: 15.5" x 11.5" x 3"(Thickness can be expanded up to 4"). Our Accordion fireproof document box adopts a multi-layer design that can meet all your storage needs. These include 13 accordion Pockets with labels,1 zipper pocket,4 pen slot,14 card slots,4 passport holder,4 small mesh bags,2 mesh bags,and 1 main pocket. It can store your important documents,money,passport,U Disk,cards,laptop,certificates in a safe and orderly way. Perfect for daily file filing and storage
- Fireproof File Organizer with Lock: Protect your valuables with the built-in high-quality combination lock (No keys required). Featuring a double metal zipper for convenient opening and closing. Design with a strong handle for carrying everything you needed easily. The fireproof file folder is suitable for business, travel, office, school, home storage, you can be 100% sure that your important documents are in a safe place. Of course, giving it as a gift to your family is also a good choice
- Trusted after sales service: Nothing is completely foolproof, but added protection is always a good idea. In an emergency, our fireproof document organizer ensures your files stay intact, giving you time to save your important documents. It is lighter, easier to carry than fireproof safes and quick to grab and go. If there any quality problem, please feel free to let us know. We are committed to solving your problem immediately, your suggestion has a great impact on the upgrade of our products
UK example: TH March’s watch requirements
TH March’s UK guidance illustrates how precise policy-specific rules can be. It asks for a valuation no more than three years old and states that a watch valued over £1,000 must have a valuation supplied within 30 days of the insurance start. It calls for new replacement value for a newly purchased watch and second-hand replacement value for a pre-owned one. These pound thresholds, age rules, and deadlines apply to the TH March example; they should not be applied to US coverage or another insurer’s policy.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Compare the policy terms, not just the premium
Use the same watch, location, and intended use when asking insurers for quotes. Compare the actual wording and schedule for each of these points:
| What to compare | Questions to ask |
|---|---|
| Type of cover | Will the watch remain under contents coverage, be scheduled under an endorsement or floater, or need separate valuables cover? |
| Limits and value | What are the per-item and aggregate limits? What value evidence is accepted, and what amount will be shown on the schedule? |
| Covered events | Does the policy cover theft, accidental damage, loss, or unexplained disappearance? What exclusions and proof requirements apply? |
| Deductible and settlement | What deductible applies? Is a claim settled through repair, replacement, agreed value, or another policy-defined method? Are any increases conditional or capped? |
| Travel and movement | Where does coverage apply while traveling? What terms apply during repair or shipment? |
| Eligibility and price | Will the insurer cover this particular watch at your location on the requested terms, and what is the quote for that coverage? |
Features differ even among specialist options. Travelers describes agreed-value settlement for scheduled jewelry and fine art, while settlement for other items depends on item type and loss details. Jewelers Mutual describes an automatic coverage-limit adjustment process every two years when a watch appraisal is more than two years old at renewal; that is a product-specific mechanism, not a general appraisal-expiry rule. Read the policy form and ask how its terms apply to your watch.
Rank #3

- FIREPROOF: The safe is UL Classified to endure 1/2 hour at 1550°F to protect irreplaceable documents, small valuables, DVDs, and USBs from fire
- WATERPROOF: The safe is ETL Verified for 72 hours of water submersion offering peace of mind in the event of a flood
- COLOR: Dark Gray Color offers a sleek and professional appearance
- MEASUREMENTS: Exterior: 16. 6 in. W x 13. 8 in. D x 14. 1 in. H; Interior: 12 in. W x 8. 1 in. H x 11. 6 in. H; large capacity 0. 66 cubic feet; weighs 41 pounds
- DURABLE: Fireproof lock box features a flat key lock to prevent the lid from opening in the event of a fire; includes two keys
Save the accepted records and keep them current
Keep the policy schedule, accepted appraisal or other value evidence, receipts, and photos together, with a protected backup. Liberty Mutual suggests secure storage such as cloud backup or a fireproof safe and recommends updating an inventory after new acquisitions. Chubb advises tracking market value periodically. At renewal—or after a material change in replacement cost—ask the insurer whether the scheduled amount remains appropriate and whether it needs updated documents.
Recommended Free Tools
Keep claim evidence ready
If the watch is lost or damaged, follow the policy’s notice and documentation requirements. Record when and where the event occurred and the relevant circumstances; Chubb recommends keeping detailed notes that include date, time, and location. TH March says that a claim made before acceptable valuation documents have been supplied still requires proof of ownership and evidence of value and may require additional information.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.