Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Start with your homeowners or renters policy: check its watch and jewelry limits, deductible, covered losses, and coverage away from home. If those terms leave a gap, ask about scheduling individual pieces or compare a separate valuables policy. The right choice depends on your collection and the insurer’s contract, so confirm requirements and settlement terms before relying on coverage.
Does homeowners or renters insurance cover watches and jewelry?
Often, watches and jewelry are covered as personal property under a homeowners or renters policy, but that does not necessarily mean a valuable piece is insured for its full value. Policies may apply a category sublimit to jewelry, restrict which losses are covered, or leave you responsible for a deductible. The National Association of Insurance Commissioners (NAIC) advises consumers to check limits and consider additional coverage when the policy is insufficient (NAIC homeowners and renters guidance; NAIC jewelry guidance).
As an Amazon Associate I earn from qualifying purchases.
Read both your declarations page and the policy wording. Look for:
- Personal-property limits and any separate watch or jewelry sublimit, including whether it applies per item or to the category as a whole.
- Covered causes of loss: for example, whether theft, accidental damage, loss, or misplacement is covered.
- Your deductible and how it applies to a jewelry or watch claim.
- Where coverage applies, including while traveling, away from home, or when an item is in storage.
Do not infer coverage from a general description of personal property. The contract and any endorsements determine what is covered, up to what amount, and under what conditions.
#1 Best Overall

- Read Before You Buy — No Video Output: These adapters support charging and USB 2.0 data transfer, but cannot transmit video signals. Except for standard USB webcams (which use USB data only), they are not compatible with HDMI/DisplayPort cables, video-capable USB-C hubs, or docking stations with video output.
- Convert USB-A Ports to USB-C: Designed to connect USB-C earphones, cables, flash drives, card readers, and other USB-C accessories to standard USB-A ports. Plug-and-play with no drivers or software required.
- Aluminum Alloy Housing: Built with a sturdy aluminum alloy shell that aids in heat dissipation and protects against daily wear and scratches. Designed to maintain a stable and secure connection.
- Compact & Travel-Friendly: The ultra-compact design allows the adapter to stay plugged into your device without blocking adjacent ports or adding bulk, reducing wear and tear on your original USB ports.
- 12-Month Warranty: Backed by a 12-month manufacturer warranty for peace of mind. Designed to meet strict quality control standards for reliable everyday performance.
What are the ways to insure a valuable collection?
Keep the existing policy
If the limits, covered losses, deductible, and geographic scope suit your collection, your current policy may be enough. Confirm the result with your insurer, especially if several pieces share one category limit.
Schedule specific pieces
A scheduled personal-property endorsement identifies named items for additional or broader coverage under an existing policy. Ask how the endorsement handles the listed value, deductible, covered losses, newly acquired items, and claims. Those terms are contract-specific; scheduling a piece does not by itself establish that every kind of loss is covered.
Rank #2

- 5-in-1 USB-C Hub: Experience comprehensive connectivity featuring a Power Delivery input, two USB-A 2.0 ports, a USB-A 3.0 port, and an HDMI port. (Note: The USB-C power delivery input port is only for connecting an external wall charger to power your laptop and cannot power peripheral devices.)
- 90W Pass-Through Charging: Achieve optimal charging with 90W pass-through power to your laptop, supported by a total input of 100W, with the hub reserving 10W for operational efficiency. (Note: Wall charger not included.)
- Quick Data Transfers: Accelerate your productivity with rapid data transfers using a high-speed 5Gbps USB 3.0 port and two 480Mbps USB 2.0 ports.
- 4K HDMI Display: Enhance your visual experience with a hub capable of delivering 4K resolution at 30Hz in both mirror and extend modes. Please note that this hub is compatible with MacBook (macOS 12 and newer), Windows 10 and 11, ChromeOS, and laptops equipped with DP Alt Mode and Power Delivery. Note: This device is not compatible with Linux.
- What You Get: Anker USB-C Hub (5-in-1, 4K HDMI), welcome guide, 18-month warranty, and our friendly customer service.
Compare a standalone valuables policy
A separate jewelry or valuables policy may be another option for a collection. Compare its contract with your existing policy rather than relying on a marketing summary. Check the covered losses, deductible, settlement basis, claims terms, eligibility, and whether a claim could affect other insurance you hold. Availability and terms vary by state and insurer.
Do these 3 things before closing this tab:
1Scan for outdated or missing drivers - takes under a minute2Clear out junk files and repair common Windows errors3Fix the driver behind crashes, sound loss and screen glitchesChoose between blanket and scheduled coverage
Some insurers offer blanket coverage for a group of articles, while scheduled coverage identifies particular pieces. A blanket limit can be simpler for lower-value items, but its per-item or per-claim caps may not fit a costly watch or jewel. For example, Acuity’s product page, accessed October 9, 2026, states that its blanket jewelry coverage has a maximum of $25,000 per claim and $5,000 per piece; it recommends scheduling items above $5,000 and typically requests an appraisal for an individual item exceeding $20,000. These are Acuity-specific terms, not general insurance thresholds (Acuity jewelry coverage).
Rank #3

- Sleek 7-in-1 USB-C Hub: Features an HDMI port, two USB-A 3.0 ports, and a USB-C data port, each providing 5Gbps transfer speeds. It also includes a USB-C PD input port for charging up to 100W and dual SD and TF card slots, all in a compact design.
- Flawless 4K@60Hz Video with HDMI: Delivers exceptional clarity and smoothness with its 4K@60Hz HDMI port, making it ideal for high-definition presentations and entertainment. (Note: Only the HDMI port supports video projection; the USB-C port is for data transfer only.)
- Double Up on Efficiency: The two USB-A 3.0 ports and a USB-C port support a fast 5Gbps data rate, significantly boosting your transfer speeds and improving productivity.
- Fast and Reliable 85W Charging: Offers high-capacity, speedy charging for laptops up to 85W, so you spend less time tethered to an outlet and more time being productive.
- What You Get: Anker USB-C Hub (7-in-1), welcome guide, 18-month warranty, and our friendly customer service.
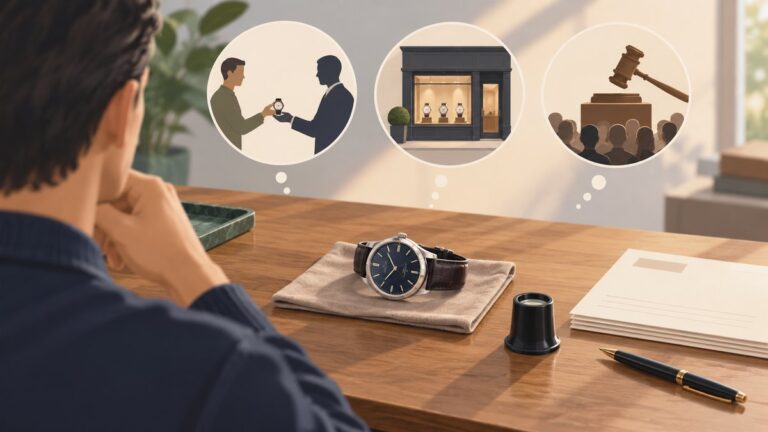
Do you need an appraisal to insure a watch or jewelry?
There is no single appraisal rule that applies to every insurer or item. Ask your insurer what valuation documents it accepts, whether an appraisal is required for your piece, how recent it must be, and whether a threshold applies. A receipt, prior appraisal, or other record may be relevant, but do not assume one will satisfy the insurer’s requirements.
Requirements differ across insurers. Progressive’s watch-insurance page, updated June 25, 2026, says it requires an appraisal for watches valued at $5,000 or more; that is a Progressive-specific requirement, not an industry-wide rule (Progressive: How to Insure a Watch). Chubb’s US jewelry page, accessed October 9, 2026, says it requires appraisals for individual jewelry pieces valued at $100,000 or more. Its page also describes automatic coverage for newly acquired pieces for up to 90 days and up to 25% of itemized coverage. These are Chubb’s stated offering terms, which should be confirmed with the insurer and are not general rules for other policies (Chubb jewelry insurance).
Rank #4

- Dual Converters, Infinite Potential:Includes 2× USB C male to USB A female adapters and 2× USB A male to USB C female adapters. Perfect for a wide range of uses—tablets with Bluetooth keyboards, expand USB ports on macbook, and more. Two different converters for all your daily needs
- Next-Level 10Gbps & 3A Charging: No more slow 480Mbps, this usb to usb c adapter has a transfer speed of up to 10Gbps, allowing you to do more transferring in less time. This usb adapter fits both USB A and USB C charger, supporting up to 3A fast charging
- Upgraded Exquisite Craftsmanship: With an aluminum alloy housing and metal connector, the usbc to usb adapter is extremely durable and sturdy. Rigorously tested to withstand more than 10,000 times of plugging and unplugging, ensuring long-lasting performance
- Broad Compatible: The usb c to usb adapter widely supports all USB C/ USB A devices like laptops, tablets, cellphones, car chargers, and phone chargers. Such as compatible with MacBook Pro/Air 2023/2022, Thunderbolt 4/3 Devices,Apple MagSafe Watch 9/8/7/SE/Ultra, iPad Pro 2022/2021, Samsung Galaxy S23/S20/S10, and iPhone 17/16/15 Pro. Plug and play
- Please Note: To reach 10Gbps speed, keep the cable under 3.3 ft. For USB A Male to USB C adapters, try flipping the USB C connector. USB C Male to USB A adapters support bidirectional 10Gbps transfer within 3.3 ft
An appraisal helps document value, but ask how the policy actually settles a claim. Depending on the contract, settlement may use a specified value, repair, replacement, or another method. Do not equate an appraisal amount with a guaranteed claim payment unless the policy says so.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteWhat should you compare before choosing coverage?
Use the policy wording and insurer’s answers to compare options on the same terms:
Best Value

- 5-in-1 Connectivity: Equipped with a 4K HDMI port, a 5 Gbps USB-C data port, two 5 Gbps USB-A ports, and a USB C 100W PD-IN port. Note: The USB C 100W PD-IN port supports only charging and does not support data transfer devices such as headphones or speakers.
- Powerful Pass-Through Charging: Supports up to 85W pass-through charging so you can power up your laptop while you use the hub. Note: Pass-through charging requires a charger (not included). Note: To achieve full power for iPad, we recommend using a 45W wall charger.
- Transfer Files in Seconds: Move files to and from your laptop at speeds of up to 5 Gbps via the USB-C and USB-A data ports. Note: The USB C 5Gbps Data port does not support video output.
- HD Display: Connect to the HDMI port to stream or mirror content to an external monitor in resolutions of up to 4K@30Hz. Note: The USB-C ports do not support video output.
- What You Get: Anker 332 USB-C Hub (5-in-1), welcome guide, our worry-free 18-month warranty, and friendly customer service.
- Covered losses: Check theft, accidental damage, loss, and misplacement individually; a policy may not treat them alike.
- Where coverage applies: Ask about travel, losses away from home, and storage. Do not assume a policy is worldwide.
- Limits and documentation: Compare per-item and aggregate limits, appraisal requirements, and any conditions for adding or updating an item.
- Deductible: Establish the amount and whether it applies to scheduled property or a separate policy claim.
- Claim settlement: Ask whether the contract provides for repair, replacement, actual cash value, agreed value, or another basis, and how that basis is determined.
- New acquisitions: Check whether newly acquired pieces receive temporary coverage, its duration and cap, and what you must do to keep them insured.
- Claims and cost: Compare premiums, reporting deadlines, claim procedures, and whether filing could affect another policy.
- Insurer information: Consider financial strength and claims information as part of the comparison. The NAIC recommends comparing coverage for theft, loss, and damage, geographic scope, deductible, and an insurer’s financial and claims history (NAIC homeowners insurance shopping tool).
What records should you prepare?
Create a secure inventory before you need to make a claim. The NAIC recommends keeping photos and appraisal copies in a home inventory and periodically reappraising valuable items (NAIC homeowners and renters guidance; NAIC jewelry guidance).
- Record each item’s brand, model or reference number if available, description, materials, distinguishing marks, serial number where applicable, and acquisition date.
- Take clear photographs from multiple angles and keep them with the inventory.
- Save receipts, appraisals, certificates, and relevant maintenance or repair records.
- Ask the insurer which valuation documents it accepts, whether it sets an appraisal-age limit, and whether individual-value thresholds apply.
- Keep copies in a secure, backed-up location separate from the collection. Update the inventory after a purchase, sale, or material change in value.
NAIC consumer guidance says an item’s dollar value has the most influence on its premium and deductible, underscoring the importance of an accurate valuation (NAIC, “Learn How to Insure Expensive Jewelry & Gifts”). Actual pricing and underwriting depend on the insurer and policy.
How should you protect the collection and keep coverage current?
Review your inventory and scheduled values when you acquire or sell a piece, or when its value changes materially. Ask your insurer whether it needs a new valuation document and what you must do to update coverage. NAIC advises consumers to ask whether a home safe, alarm system, or safe-deposit box may qualify for a discount; availability is insurer-specific, so confirm before counting on savings (NAIC homeowners and renters guidance). A safe can also be considered as a storage measure, but it does not replace insurance.
A warranty is not a substitute for insurance: a warranty may address defects, while insurance addresses only the losses specified in its contract. Check each document for what it covers.
This guide is general information for US consumers, not individualized insurance advice. Policy language, eligibility, appraisal rules, rates, limits, and availability vary by insurer and state. Confirm details with your insurer or a licensed agent and rely on the policy contract for the final terms.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.